Financial decisions often become more complex as income, assets, and personal responsibilities grow. Research from the Financial Consumer Agency of Canada shows that Canadians benefit from understanding financial products and seeking appropriate guidance when making important financial decisions. Choosing the right type of professional is part of that process because different advisors specialize in different levels of planning.
Many Canadians comparing financial advisor vs wealth manager Canada discover that the primary distinction lies in the breadth of services offered and the complexity of a client’s financial situation. While both professionals can help clients pursue financial goals, one generally focuses on specific financial products or planning needs, while the other coordinates multiple areas of a person’s financial life.
1. Consider How Complex Your Financial Life Has Become
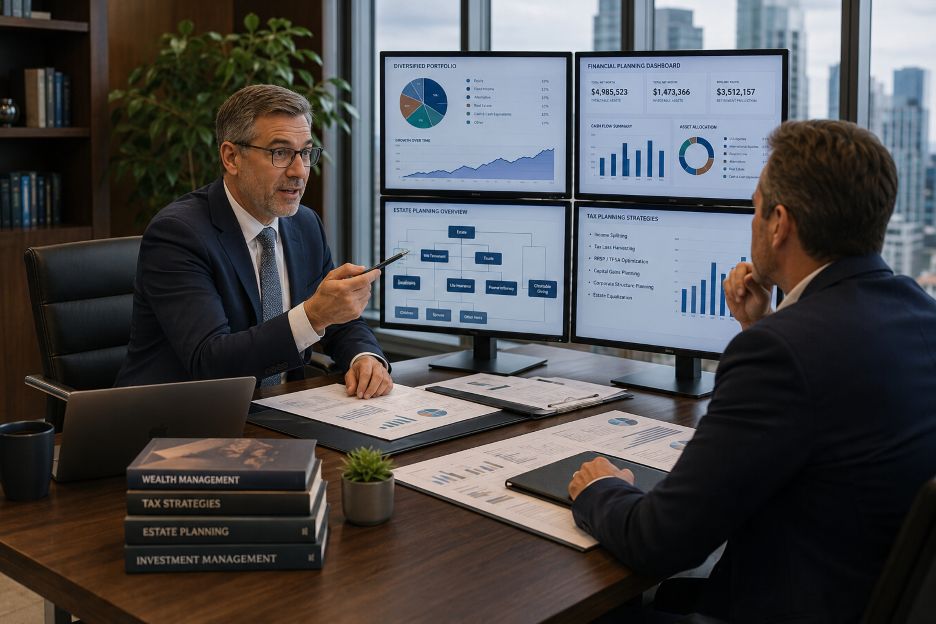
The biggest indicator is often the number of financial decisions you must manage simultaneously. A financial advisor may help with investments, retirement planning, insurance, or education savings. A wealth manager typically oversees all of these areas while coordinating tax planning, estate considerations, business succession, charitable giving, and risk management.
Experts at the Canadian Investment Regulatory Organization (CIRO) note that financial professionals may provide different services depending on their registration, credentials, and areas of expertise. Understanding those differences helps clients select the appropriate level of support.
2. Evaluate Your Net Worth
Higher net worth does not automatically require wealth management, but increasing assets often create additional planning needs. Multiple investment accounts, taxable assets, trusts, investment properties, and family wealth transfers require coordination that extends beyond selecting investments.
Reports from the CFA Institute explain that comprehensive wealth management integrates investment advice with broader financial decision-making rather than treating each issue independently.
3. Ask Whether Taxes Affect Most Financial Decisions
Taxes influence retirement withdrawals, investment choices, charitable donations, business income, and estate transfers. When several financial decisions carry significant tax implications, coordinated planning becomes increasingly valuable.
Research published by the Chartered Professional Accountants of Canada highlights the importance of tax-efficient planning throughout every stage of wealth accumulation and retirement preparation. Financial professionals who coordinate with tax specialists may help reduce unnecessary complexity while supporting long-term goals.
4. Think About Business Ownership
Business owners often face financial questions that extend beyond personal investing. Compensation structures, corporate investments, succession planning, shareholder agreements, and retirement strategies frequently overlap.
Guidance from the Business Development Bank of Canada indicates that entrepreneurs benefit from integrated planning because business assets and personal finances are closely connected. A professional who understands both areas can help align personal and corporate objectives.
5. Look at How Many Professionals You Already Work With
If you already have an accountant, lawyer, insurance specialist, and investment advisor, coordinating decisions can become challenging. A wealth manager often acts as the central point of communication among these professionals, helping ensure recommendations work together rather than independently.
Studies published by the Financial Planning Standards Council, now part of FP Canada, have consistently emphasized that comprehensive financial planning involves integrating multiple disciplines into a unified strategy.
6. Consider Your Family Situation
Major life events often increase planning needs. Marriage, divorce, caring for aging parents, supporting adult children, blended families, or planning inheritances can introduce legal, financial, and tax considerations that require careful coordination.
Findings from FP Canada suggest that Canadians increasingly recognize the value of comprehensive financial planning during periods of significant life change because financial decisions become interconnected.
7. Review Your Investment Goals
If your primary objective is building an investment portfolio, a financial advisor may provide exactly the guidance you need. Many advisors help clients establish diversified portfolios, manage investment risk, and prepare for retirement.
Research from the Canadian Securities Administrators encourages investors to understand an advisor’s qualifications, compensation model, and services before entering a professional relationship. Matching expertise with personal objectives often produces better long-term outcomes.
8. Think Beyond Retirement Planning
Retirement remains an important financial goal, yet many households eventually need guidance that extends further. Estate planning, philanthropic giving, family trusts, intergenerational wealth transfer, and legacy planning become increasingly relevant as wealth grows.
The Organisation for Economic Co-operation and Development (OECD) has noted that ageing populations and longer retirements make integrated financial planning increasingly important for maintaining financial security over time.
9. Decide Whether You Want Ongoing Coordination or Individual Advice
Some Canadians prefer receiving advice when specific financial questions arise. Others want an ongoing relationship where one professional regularly reviews investments, insurance, tax changes, retirement progress, and evolving family goals.
Research shows that financial circumstances rarely remain static. Career changes, housing decisions, inflation, market conditions, and regulatory updates all influence long-term planning. Technology is also expanding the ways Canadians access financial guidance, with AI-powered financial advisors becoming part of broader discussions about investment planning. While digital tools can improve efficiency and provide data-driven insights, many individuals with more complex financial situations still benefit from personalized advice and coordinated planning from experienced professionals.
Conclusion
Choosing between a financial advisor and a wealth manager is less about selecting the “better” professional and more about matching expertise to your circumstances. Individuals with straightforward financial needs may benefit from focused advice on investments or retirement planning. Those managing larger asset bases, businesses, multiple financial disciplines, or complex family situations often require broader coordination.
The Financial Consumer Agency of Canada, CIRO, and FP Canada all encourage Canadians to understand the qualifications, responsibilities, and services provided by financial professionals before making decisions. As financial lives continue to evolve, selecting guidance that fits both current needs and future complexity can help create a more organized and informed financial strategy.
 The Insurance Surgery understands how complicated, confusing and laborious it could be to find a life insurance policy to match you as well as your circumstances where you submit or send your information repeatedly so you can hear back from individual insurance providers. With The Insurance Surgery, the process is made easier and quicker for you as they only take your information once and make use of their expert knowledge and skills to look for the best insurance provider for you.
 Track Spending and Cut Costs
 “It takes money to make money.”
 Business Financial Management And Planning
 Availability of Sufficient Funds